Share
Share
Share
Share
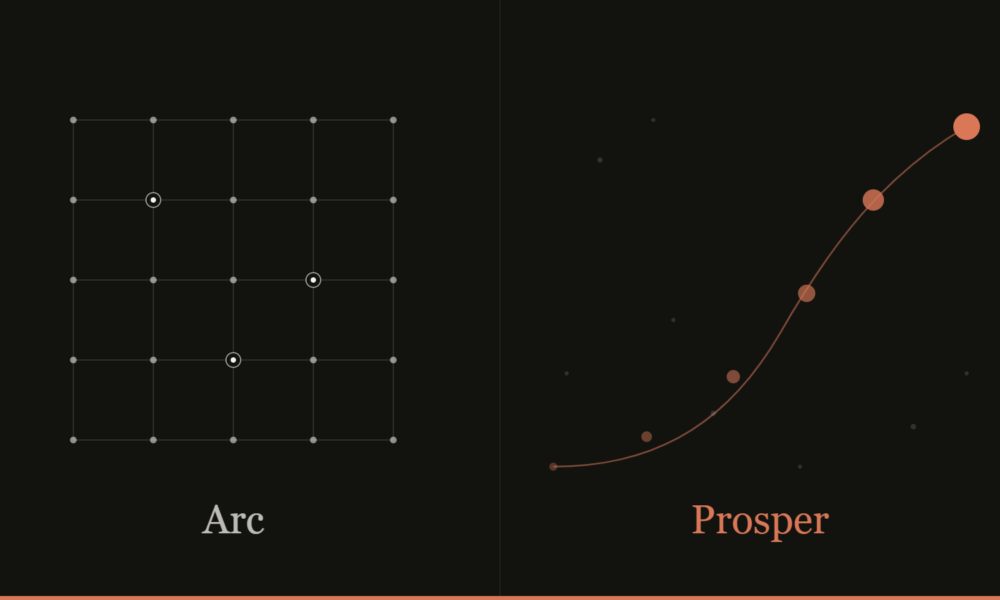
This week’s headlines made it easy to lump a lot of very different launches into one category. Circle switched on Arc mainnet. Various meme launchpads kept doing what they do. And Prosper launched Performance Markets on Pharos, under a framework it calls MemeRWA, a name that invites exactly the flattening it shouldn’t get.
Calling Prosper a launchpad isn’t wrong, but it hides more than it reveals. Most meme launchpads exist to launch tokens with no underlying activity behind them. A token goes live, trades on attention, and either finds a community or doesn’t. There is no strategy, no performance data, no mechanism connecting the token’s supply to anything happening in the real world. That is the model the term “launchpad” has trained people to expect.
Prosper does something structurally different. Every token it launches is tied to a specific trading vault. A curator with an onchain track record deploys a vault, investors buy shares that move with its net asset value, and alongside those shares the vault launches a second token, p{VAULT}, sold through a public bonding curve with nothing set aside for insiders. The two instruments are deliberately separate. Shares represent the strategy. The token represents something else entirely.
Laura Shi, Chief Business Officer at Pharos, where she leads business architecture, RealFi innovation and ecosystem expansion, explains what that separation is meant to do:
“Think of p{VAULT} as a token built around a public track record, not a share in a fund. Anyone can see how the Curator and the strategy are performing onchain, and use that information to decide what the token is worth. Strong results may build confidence; weak results may reduce it. But there is no automatic one to one link to the Vault’s NAV. Buyback and burn affects supply, it does not promise price support.”
That distinction, a token informed by performance but not owned by it, is the entire point of the design. A high-water mark, the standard hedge-fund mechanism that only credits a manager with fees on gains above the fund’s previous peak, decides when a share of those fees buys p{VAULT} back on the open market and burns it. A strategy that keeps setting new highs keeps shrinking its token’s supply. A strategy that stalls generates nothing, and the token is left entirely to what the market thinks of it.
Compare that with Arc’s own token event this same week. Circle minted 10 billion ARC tokens as a technical step, explicitly not a commitment to a public launch, tied to a possible future move to proof of stake. Two very different relationships between a token and the thing it is supposed to represent, happening in the same seven days, under headlines that could easily read as the same story.
The useful distinction isn’t “launchpad” versus “not a launchpad.” It’s what backs the token once it exists. A typical meme launchpad backs it with nothing but attention. Arc’s ARC token backs it with the infrastructure of a permissioned settlement chain, still finding its public footing. Prosper’s p{VAULT} backs it with a live, onchain performance signal that anyone can verify, without pretending that signal is a claim on the underlying assets.
Whether that distinction holds up under real market pressure, whether curators show up in numbers, whether the first vaults clear their high-water marks in public, is still an open question. But the framework itself deserves to be evaluated on its own terms, not folded into a category built for something else entirely.
For information purposes only. Crypto carries risk. Not financial advice!