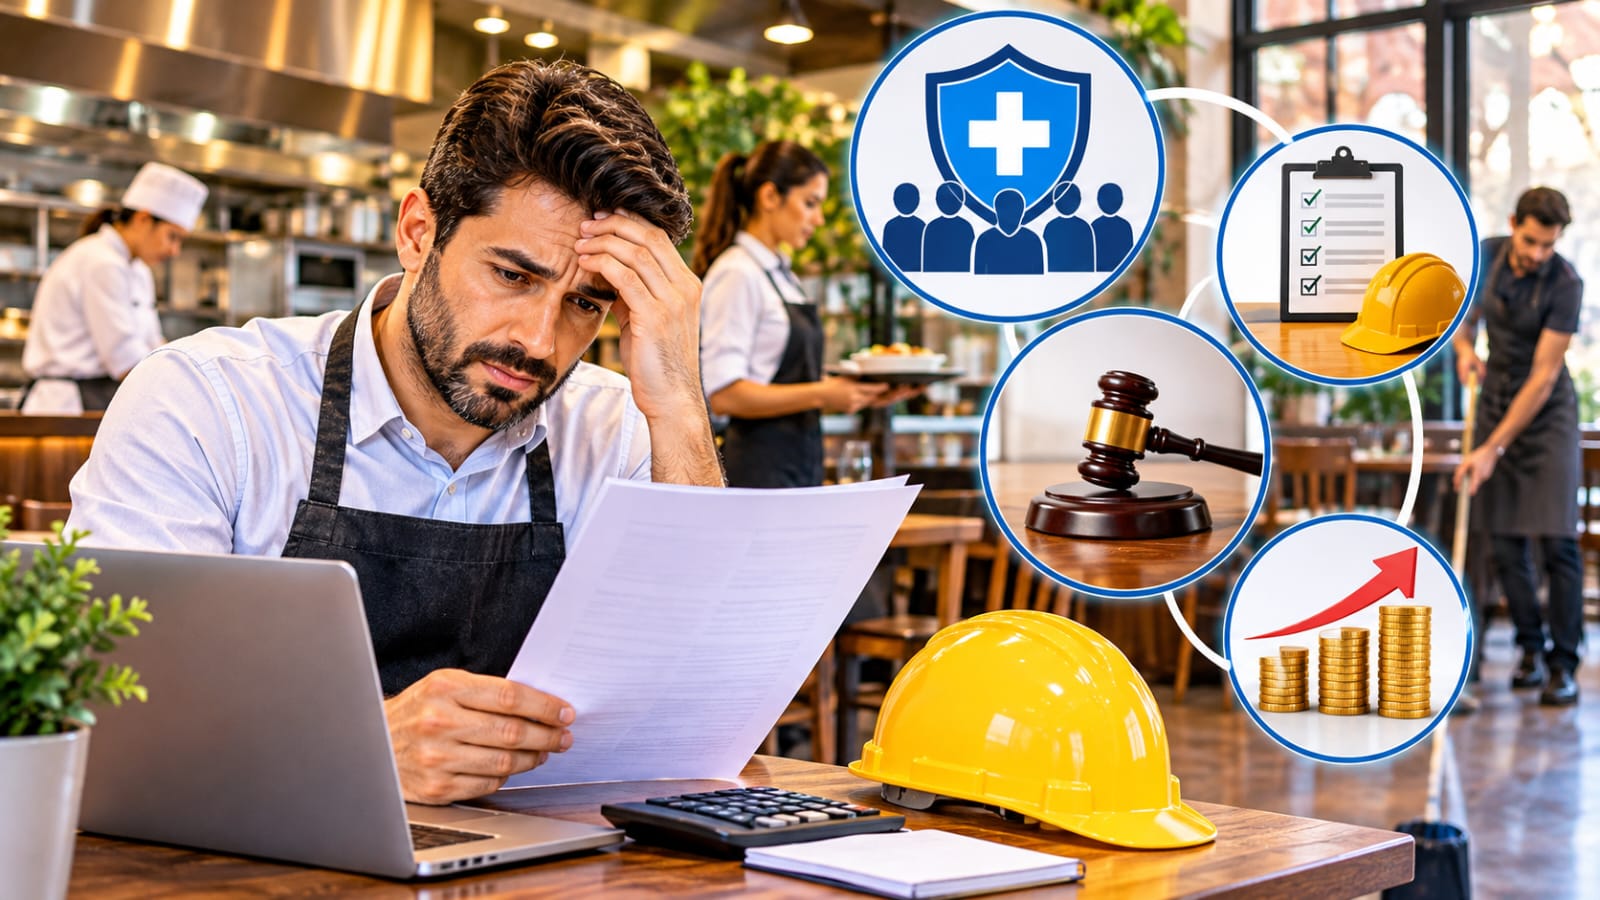
Running a restaurant in New Jersey means managing a continuous chain of operational decisions — staffing, scheduling, vendor relationships, food safety, and customer experience. Workers’ compensation insurance sits somewhere in the background of that chain, often treated as a fixed administrative cost rather than an active risk management tool. That treatment is where the financial exposure begins.
Workers’ comp claims in the restaurant industry are among the most frequent across all sectors. Kitchens involve open flames, sharp equipment, wet floors, and workers moving quickly under pressure. Dining rooms involve physical labor, repetitive motion, and guest-facing stress. Delivery and catering operations extend liability beyond the building itself. When an injury occurs, the financial consequences depend less on the nature of the injury and more on the choices the owner made before anyone got hurt.
New Jersey’s workers’ compensation requirements are well-defined under state law, but the gap between legal compliance and practical protection is wider than most operators realize. The mistakes outlined here are not edge cases. They appear regularly, often in well-run restaurants, and they almost always could have been avoided with earlier attention to how the policy was structured, managed, and documented.
Misclassifying Employees and the Premium Consequences That Follow
Workers’ compensation premiums in New Jersey are calculated based on job classification codes assigned to each employee role. These codes reflect the statistical risk associated with the work being performed. A dishwasher, a line cook, a bartender, and a delivery driver each carry different risk profiles and are assigned different codes. When owners — or even some brokers — assign codes incorrectly, the premium calculation becomes inaccurate from the start.
For restaurant owners comparing options or reviewing their coverage, working with a broker who specializes in restaurant insurance new jersey operations can help ensure that classifications are applied correctly and that the policy structure actually reflects how the business runs.
Misclassification creates two distinct problems. The first is financial: if employees are under-classified into lower-risk categories, the owner may face a significant audit adjustment at the end of the policy term when payroll and roles are verified. That adjustment arrives as an unexpected bill, sometimes substantial. The second problem is coverage risk: if roles are misrepresented during the policy application, insurers may dispute claims on grounds that the injured worker was engaged in duties not reflected in the policy.
How Payroll Audits Expose Classification Errors
Most commercial workers’ comp policies include an end-of-term payroll audit. The insurer reviews actual payroll records, compares them against what was reported at policy inception, and recalculates the premium accordingly. If a restaurant owner listed ten employees as servers but five of them regularly performed kitchen prep work, that reclassification will occur during the audit — not at renewal, not proactively, but after the fact.
The practical consequence is that the audit-generated invoice arrives outside of the normal billing cycle, often when cash flow is already stretched. Restaurants operating on thin margins feel these adjustments acutely. Maintaining accurate role descriptions and updating the insurer when duties change materially is not paperwork overhead — it is a direct financial control measure.
Carrying Inadequate Coverage Limits During Peak Operating Periods
Restaurant operations are not static. A location that runs with a core team of twelve employees during regular service may expand significantly during holidays, catering seasons, or special events. Temporary and seasonal workers added during these periods are still covered under New Jersey workers’ compensation law, but the policy limits and structures need to reflect the expanded workforce to function properly.
Some owners treat their base policy as sufficient for peak periods, assuming the insurer will account for temporary headcount increases automatically. That assumption is not always supported by the policy terms. When a seasonal hire is injured during a period when their role was not reported or accounted for in payroll estimates, the claim process becomes more complicated and the financial exposure increases.
The Risk of Underreporting Projected Payroll
At policy inception, insurers ask for projected annual payroll figures. These projections form the basis for the initial premium calculation. If an owner underreports projected payroll — either to reduce upfront costs or simply due to inaccurate forecasting — the premium paid during the policy year will not reflect actual exposure. The payroll audit will then generate a correction that the owner must fund out of pocket.
Beyond the financial adjustment, underreported payroll can complicate the claims process itself. Insurers reviewing a large claim may scrutinize the original policy application for discrepancies. Any inconsistency between reported payroll and actual employment creates friction that slows resolution and may require legal involvement to settle.
Delaying Injury Reports Beyond the Required Window
New Jersey requires that workplace injuries be reported to the insurer within a specific timeframe. Many restaurant owners are aware that reporting requirements exist, but the operational pace of food service — managing shifts, covering roles, addressing immediate service needs — can push administrative tasks aside. A worker who is injured on a Friday night during a busy dinner service may not have that injury formally reported until the following week.
Late reporting is one of the most consistent factors that complicates workers’ compensation claims. It raises questions about the nature, timing, and cause of the injury. It limits the insurer’s ability to manage the medical care pathway from the outset. And in New Jersey, delays can affect both the employer’s legal standing and the worker’s access to benefits.
Why Immediate Documentation Matters More Than Speed Alone
The quality of initial documentation matters as much as the timing. A reported injury that lacks specifics — where it happened, what the worker was doing, who witnessed it, what the immediate condition appeared to be — leaves room for dispute later. The U.S. Department of Labor’s Office of Workers’ Compensation Programs emphasizes consistent incident documentation as a foundational element of effective claims management.
Restaurants benefit from maintaining a simple, accessible incident log that any manager on duty can complete without specialized training. This does not need to be complex. It needs to be consistent and completed at the time of the incident, not reconstructed afterward from memory.
Skipping Safety Documentation That Directly Affects Claims Outcomes
Workers’ compensation insurers in New Jersey assess not just the injury itself but the context in which it occurred. When an injured worker files a claim, the insurer and potentially a court will review whether the employer maintained a reasonably safe working environment. Safety protocols, training records, and equipment maintenance logs all contribute to this assessment.
Many restaurant owners manage safety practices informally. Training happens verbally. Equipment issues are addressed as they arise. These practices may be adequate day-to-day, but they create a documentation gap that becomes significant during claims review. The absence of records does not prove negligence, but it removes the employer’s ability to demonstrate due diligence.
How Safety Records Influence Experience Modification Rates
Workers’ comp premiums in New Jersey are partly determined by an experience modification rate, often called an EMR, which reflects the employer’s historical claims record relative to others in the same industry. A history of frequent or costly claims drives the EMR upward, increasing future premiums. A consistent track record of safe operations and properly managed claims can lower it over time.
Safety documentation supports lower EMR outcomes in two ways. First, it reduces the likelihood that incidents escalate into claims by ensuring conditions are regularly monitored and corrected. Second, when claims do occur, documentation helps establish the context that leads to faster, more accurate resolution — which limits total claim costs and their downstream effect on the modification rate.
Misunderstanding the Scope of Independent Contractor Exclusions
Some restaurant owners reduce their workers’ comp costs by classifying workers as independent contractors. The logic is straightforward — independent contractors are not employees, and workers’ compensation obligations under New Jersey law generally apply to employees. However, the legal definition of an independent contractor in New Jersey is specific and narrow, and misapplication of that classification creates serious risk.
New Jersey applies an ABC test to determine whether a worker qualifies as an independent contractor for workers’ comp purposes. If a worker performs services that are part of the core business operation, works under the direction of the employer, and does not independently operate in a separate trade, they will likely be classified as an employee under state law — regardless of what the working agreement says.
The Legal and Financial Exposure of Misclassification
When a worker classified as an independent contractor is injured and that classification is challenged, the restaurant owner may be found liable for benefits that were never insured. This includes medical costs, lost wage replacement, and potential legal fees. In some cases, New Jersey regulators may also impose penalties for willful misclassification. The financial exposure from a single such claim can far exceed any premium savings accumulated over time.
Failing to Coordinate Return-to-Work Programs With the Insurance Process
When an injured employee is recovering, the absence of a return-to-work structure creates a longer, more costly claims period. New Jersey workers’ comp law accounts for modified duty assignments — temporary roles that accommodate physical limitations while the worker continues to earn wages. Many restaurant owners either do not know this option exists or do not have the processes in place to offer it.
Modified duty positions in a restaurant context can include host duties, administrative tasks, inventory management, or limited front-of-house responsibilities that do not require the physical demands of the injured worker’s regular role. When these options exist and are communicated properly to the insurer, the total cost of the claim often decreases because wage replacement payments are reduced or eliminated.
Renewing Coverage Without Reviewing What Changed in the Business
Restaurant operations change. Menu concepts shift. Service formats evolve. Locations open or close. Staff sizes fluctuate. Many owners renew workers’ compensation coverage each year by simply accepting the renewal terms from their insurer without reviewing whether the policy still reflects current operations. This passive approach can create coverage gaps as well as overpayment for roles or locations that no longer exist.
A coverage review at renewal should account for any changes to the workforce, the job roles performed, the physical locations covered, and any new service lines added since the previous policy period. For operators navigating restaurant insurance new jersey requirements across multiple locations or with varied service formats, this review matters more because the exposure profile is more complex.
How Coverage Gaps Form During Business Changes
Coverage gaps rarely appear as obvious absences. They form gradually, as business operations outpace the policy terms that were written at an earlier point in time. A catering program added after the policy was written, a second kitchen space leased mid-year, or a shift to late-night service that changes who is working and when — each of these changes has implications for the workers’ comp policy that passive renewal does not address.
Reviewing coverage annually with a broker who understands current restaurant insurance new jersey requirements ensures that the policy remains aligned with what the business actually does, not what it did when the policy was first written.
Closing Thoughts
Workers’ compensation is not a simple compliance checkbox for New Jersey restaurant owners. It is a financial instrument with real premium implications, real legal exposure, and real consequences when claims are managed poorly. The mistakes described here are not uncommon — they appear across independent restaurants, regional chains, and long-established operations alike.
The common thread running through each mistake is the same: treating workers’ comp as a background administrative function rather than an active part of how the business manages its people and its risk. Owners who engage with their coverage — who maintain accurate classifications, document incidents properly, review policies at renewal, and understand the law governing worker status — experience fewer claim disputes, more predictable premium costs, and faster resolution when incidents do occur.
New Jersey’s restaurant environment is demanding. The labor is physical, the pace is unrelenting, and the margins are thin. That combination makes it more important, not less, to have workers’ compensation coverage that is accurate, current, and built on a clear understanding of how the business actually operates. For restaurant owners who are uncertain where their current policy stands, a direct conversation with a qualified broker is the most straightforward starting point.